Guide to Repossession Laws
📅 2026 Update: Changes in Repossession Laws
Since the original article was written, there have been important updates to repossession laws in the United States. These changes aim to enhance consumer protection and clarify the repossession process. This section highlights the key modifications, while the earlier article continues further down the page.
📈 Consumer Protection Enhancements
In 2025, the Consumer Financial Protection Bureau (CFPB) introduced stricter regulations for auto lenders. These rules require lenders to provide clearer disclosures about repossession rights and procedures. This shift should help consumers better understand their options and the risks involved.
🗓️ State-Level Reforms
Several states have taken action to protect consumers. For instance, California and New York enacted laws in 2024 that extend the notice periods before repossession. This gives borrowers more time to address missed payments and avoid losing their vehicles.
💰 Current Fees and Costs
Repossession fees have not changed much, with agents charging between $200 and $500 for vehicle recovery. However, storage fees can accumulate quickly, ranging from $20 to $50 per day after a vehicle is repossessed. Borrowers need to be aware of these costs when trying to reclaim their vehicles.
⏳ Processing Times
The notice period before repossession varies by state, typically lasting 10 to 30 days after the first missed payment. Once the vehicle is repossessed, borrowers generally have 10 to 15 days to redeem it by paying the outstanding balance, including fees.
📌 Key Points to Remember
- 📈 Stricter regulations by the CFPB enhance consumer protections.
- 🗓️ States like California and New York have extended notice periods.
- 💰 Repossession fees remain between $200 and $500, but storage fees can add up.
- ⏳ Processing times vary; borrowers usually have 10 to 15 days to reclaim vehicles.
💡 Tips for Handling Repossession Situations
Review the details of your own situation with your attorney. Understanding your rights can help you navigate the complexities of repossession laws.
📜 Understand Your Loan Agreement
It's crucial to know the terms of your loan agreement. This can help you understand what actions may lead to repossession. Knowing your rights can aid in negotiations with lenders.
📬 Watch for the Notice of Default
Lenders are required to send a Notice of Default after 30 days of missed payments. Pay attention to this notice, as it outlines your options and the timeline for repossession.
🏠 Seek Local Assistance
Many states have organizations that can help you understand your rights and options related to repossession. Look for local consumer advocacy groups or legal aid societies for support.
📅 Know the Redemption Period
After repossession, you typically have 10 to 15 days to reclaim your vehicle. Make sure you understand the payment requirements, including any additional fees.
💬 Communicate with Your Lender
If you are facing financial difficulties, communicate with your lender as soon as possible. They may offer options to help you avoid repossession, such as payment plans or loan modifications.
🏆 Ranked by User Reviews (2026)
This section reviews several services relevant to debt relief and repossession issues. The order follows Trustpilot data as of October 2026, and scores can change over time. Star ratings are only one indicator, as unhappy customers often leave more reviews, and sample sizes can differ.
🥇 1. Freedom Debt Relief
Freedom Debt Relief has been rated 4.5. It is known for its debt settlement services and credit counseling. However, some reviewers mention issues with customer service responsiveness, which can impact user experience when seeking help with debt-related problems.
🥈 2. Take Charge America
Take Charge America holds a Trustpilot score of 4.7. This organization is recognized for its credit counseling and debt management plans. However, it has limited availability in certain states, which may affect those seeking assistance.
🥉 3. Consolidated Credit
Consolidated Credit averages 4.8. It focuses on credit counseling and debt management programs. Some users report high fees for services, which is an important consideration for individuals dealing with financial strain.
4️⃣ Americor
Americor has a rating of 4.7. It is known for debt settlement and financial consulting services. Some complaints point to aggressive sales tactics, which potential clients should be aware of when considering their options.
5️⃣ Accredited Debt Relief
Accredited Debt Relief holds a 4.8 rating. It offers debt relief services and financial consulting. However, some users express dissatisfaction with settlement outcomes, which could affect their overall satisfaction.
6️⃣ ClearOne Advantage, LLC
ClearOne Advantage averages 4.8. This company provides debt relief services, financial consulting, and non-bank financial services. Some customers report high fees and long program durations, which are important factors to consider before engaging their services.
🆓 Free Government and Nonprofit Help
The Consumer Financial Protection Bureau (CFPB) offers resources and guidance on handling repossession and understanding consumer rights. Additionally, legal aid societies provide free or low-cost legal assistance to individuals facing repossession, helping them understand their options.
🔎 What to Compare When Choosing Services
- 🔍 Trustpilot scores and review counts for insights on user experiences.
- 💬 Types of services offered, like debt settlement or credit counseling.
- 💸 Fee structures, including any hidden costs or high fees.
- 🗺️ Availability in your state, as some services may not operate everywhere.
- 📞 Customer service quality and responsiveness from user feedback.
❓ Frequently Asked Questions
🤔 What happens if my vehicle is repossessed?
If your vehicle is repossessed, the lender will typically notify you. You will have a set period, usually 10 to 15 days, to reclaim it by paying the outstanding balance and any associated fees.
🚗 Can I negotiate with my lender before repossession?
Yes, you can negotiate with your lender before repossession occurs. It's best to discuss payment plans or loan modifications if you are facing financial difficulties.
📉 How does repossession affect my credit score?
Repossession can significantly impact your credit score, with effects lasting up to seven years. This can make it more difficult to obtain loans or credit in the future.
🔄 Can I get my vehicle back after it has been repossessed?
Yes, you can get your vehicle back within the redemption period by paying the outstanding balance, including any repossession and storage fees. This period typically lasts 10 to 15 days.
🏛️ Are there any state-specific rules for repossession?
Yes, repossession laws and procedures vary significantly by state. Some states may require court orders before repossession, while others have different notice periods.
💼 What resources are available for legal help?
The CFPB provides guidance on repossession and consumer rights. Additionally, legal aid societies offer free or low-cost assistance for individuals facing repossession.
⚖️ Recent Court Cases Related to Repossession
Recent court rulings have clarified aspects of repossession laws and consumer rights. These cases connect to the broader topic of repossession and the protections available to consumers facing this situation.
- Court dismisses credit reporting case against Truist BankDistrict Court, District of Columbia · September 22, 2026
- Ohio court dismisses appeal in Telhio Credit Union caseOhio Court of Appeals · June 16, 2026
- Puerto Rico court disqualifies attorney in money collection caseTribunal De Apelaciones De Puerto Rico/Court of Appeals of Puerto Rico · May 15, 2026
- Ohio Court upholds dismissal of credit union lawsuitOhio Court of Appeals · June 29, 2026
For more recent rulings, feel free to browse more rulings on the news page.
End of October 2026 Update
Guide to Repossession Laws: Everything You Need to Know
Repossession can be a daunting experience for both creditors and debtors. For a creditor, repossessing a debtor's property is not a desirable process, but it may be necessary to recover their investment. On the other hand, for the debtor, it can result in the loss of their property and may negatively affect their credit score. Repossession laws are meant to regulate the process of property repossession to ensure fairness and prevent abuse. In this article, we provide a comprehensive guide to repossession laws in the United States.
What is Repossession?
Repossession is the legal process in which a creditor can take possession of a debtor's property that was used as collateral for a loan in the event of non-payment. In other words, the creditor is entitled to take possession of the property if the debtor fails to make regular payments or breaches the terms of the loan agreement.
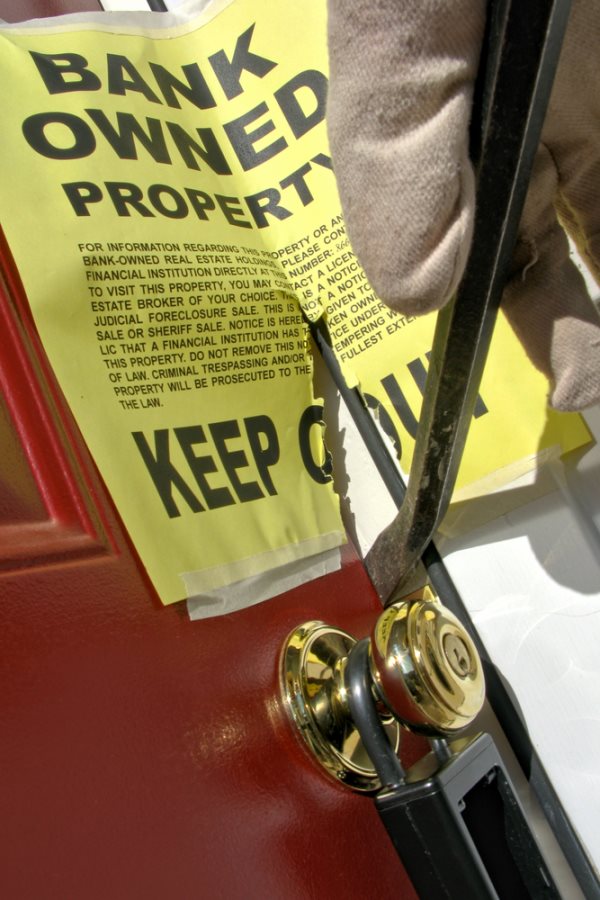
The most common types of property that are subject to repossession include vehicles, real estate, and personal property such as household appliances, furniture, and electronics.
Repossession laws vary by state, and it's important for debtors and creditors to understand the applicable laws to ensure a fair and legal process.
How Does Repossession Work?
Repossession typically occurs after the debtor fails to make payments on time or violates the terms of the loan agreement. The creditor may send a notice of default warning to the debtor, giving them a deadline to make the payments due. If the debtor fails to cure the default, the creditor may initiate the repossession process.
The creditor may have to obtain a court order to repossess the property, depending on the state's repossession laws. In some states, creditors are required to provide notice to the debtor before repossessing the property.
Once the creditor has obtained the legal right to repossess the property, they may send a repossession agent to take possession of the property. The repossession agent must follow specific regulations to ensure a legal and safe repossession process. The agent cannot use excessive force or cause unnecessary damage to the property.
After the creditor has repossessed the property, they must provide a notice of sale to the debtor, notifying them of the upcoming sale. The creditor may then sell the property to recover the debt owed by the debtor.
Repossession laws differ significantly from state to state, and it's important to become familiar with the applicable laws to ensure a fair and legal process.
Repossession Laws by State
Repossession laws in the United States vary from state to state, and it's important to become acquainted with the laws in your state to avoid any legal disputes. Some states require a court order before the creditor can repossess the property, while others don't. Here are some of the most common aspects of repossession laws in various states:
- Alabama: In Alabama, creditors don't have to provide a notice of sale to the debtor before the sale of the property. However, they must provide a notice of intent to sell before repossessing the property.
- Alaska: In Alaska, creditors must provide a notice of sale to the debtor before they can sell the property.
- Arizona: In Arizona, creditors must provide a notice of sale to the debtor at least ten days before the sale of the property.
- California: In California, creditors must provide a notice of sale to the debtor before repossessing the property.
- Colorado: In Colorado, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- Florida: In Florida, creditors must provide a notice of sale to the debtor before they can sell the property.
- Georgia: In Georgia, creditors must provide a notice of sale to the debtor before they can sell the property.
- Hawaii: In Hawaii, creditors must provide a notice of sale to the debtor before they can sell the property.
- Illinois: In Illinois, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- Indiana: In Indiana, creditors must provide a notice of sale to the debtor before they can sell the property.
- Iowa: In Iowa, creditors must provide a notice of sale to the debtor before they can sell the property.
- Kentucky: In Kentucky, creditors must provide a notice of sale to the debtor before they can sell the property.
- Louisiana: In Louisiana, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- Michigan: In Michigan, creditors must provide a notice of sale to the debtor before they can sell the property.
- Minnesota: In Minnesota, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- Missouri: In Missouri, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- Nevada: In Nevada, creditors must provide a notice of sale to the debtor before they can sell the property.
- New York: In New York, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- North Carolina: In North Carolina, creditors must provide a notice of sale to the debtor before they can sell the property.
- Ohio: In Ohio, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- Oklahoma: In Oklahoma, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
- Tennessee: In Tennessee, creditors must provide a notice of sale to the debtor before they can sell the property.
- Texas: In Texas, creditors must provide a notice of sale to the debtor before they can sell the property.
- Utah: In Utah, creditors must provide a notice of sale to the debtor before they can sell the property.
- Washington: In Washington, creditors must provide a notice of sale to the debtor before they can sell the property.
- Wisconsin: In Wisconsin, creditors don't have to provide a notice of sale to the debtor before the sale of the property.
The above list is not exhaustive, and we encourage readers to check their local repossession laws to avoid any legal disputes.
📝 See Also
Employment of Professional Repossession Services
Repossession agents are individuals or companies hired by creditors to recover and repossess their property. They may use different tactics to recover the property, including negotiation or repossession force. Additionally, repossession agents may possess specialized equipment such as towing trucks and lock-picking tools to facilitate the repossession process.
It's important for creditors to exercise caution when hiring repossession services. Repossession agents must adhere to specific guidelines during the repossession process to ensure a fair and legal recovery of the property. Failure to adhere to these regulations can result in legal disputes and negatively affect the creditor's reputation.
In conclusion
Repossession laws in the United States vary by state and include different requirements. Understanding applicable laws is fundamental for both creditors and debtors to avoid any legal disputes and ensure a fair and legal repossession process. It's important to note that the information provided in this article is for informational purposes only and should not serve as legal advice. When in doubt, it's essential to consult an experienced legal professional to discuss your specific situation and local repossession laws.